Reverse mortgages (HECM)
Stay in your home. Use what it's worth.
A reverse mortgage (HECM) lets homeowners 62 and older turn part of their home equity into cash, a line of credit or monthly payments, without a monthly mortgage payment. You keep the title and keep living in the home, and you stay responsible for property taxes, insurance and upkeep.
By Georg F. Thoma, Senior Loan Officer · NMLS 312260 · Updated
The honest version
- 01
You still own your home and are responsible for taxes, insurance and upkeep.
- 02
The loan is repaid when you sell, move out permanently, or pass away — usually from the sale of the home. You or your heirs never owe more than the home is worth.
- 03
About nine in ten borrowers take the line of credit. It grows over time and only costs you when you use it.
- 04
Independent HUD counselling is required before you apply. I think that's a good thing.
See your number first, then decide if you want to talk.
Common questions
Still stuck? Call Georg at (808) 357-9791
Who qualifies for a reverse mortgage?
At least one borrower must be 62 or older, the home must be your primary residence, and you need enough equity in it. You also meet with an independent HUD-approved counsellor before you apply.
When does a reverse mortgage have to be repaid?
When the last borrower sells, moves out permanently or passes away, usually from the sale of the home. It can also come due if property taxes, insurance or upkeep aren't kept up. You or your heirs never owe more than the home is worth.
Can my heirs keep the house?
Yes. They can repay the loan balance, often by refinancing, and keep the home. If they would rather sell, they keep whatever equity is left after the loan is repaid.
Do I still own my home with a reverse mortgage?
Yes. The title stays in your name. The lender records a lien on the home, the same as with any other mortgage.
What if my home is worth more than the HECM limit?
The federal limit caps how much of your home's value counts toward a HECM. For higher-value homes, a proprietary jumbo reverse mortgage may reach more of your equity. I'll show you both side by side.
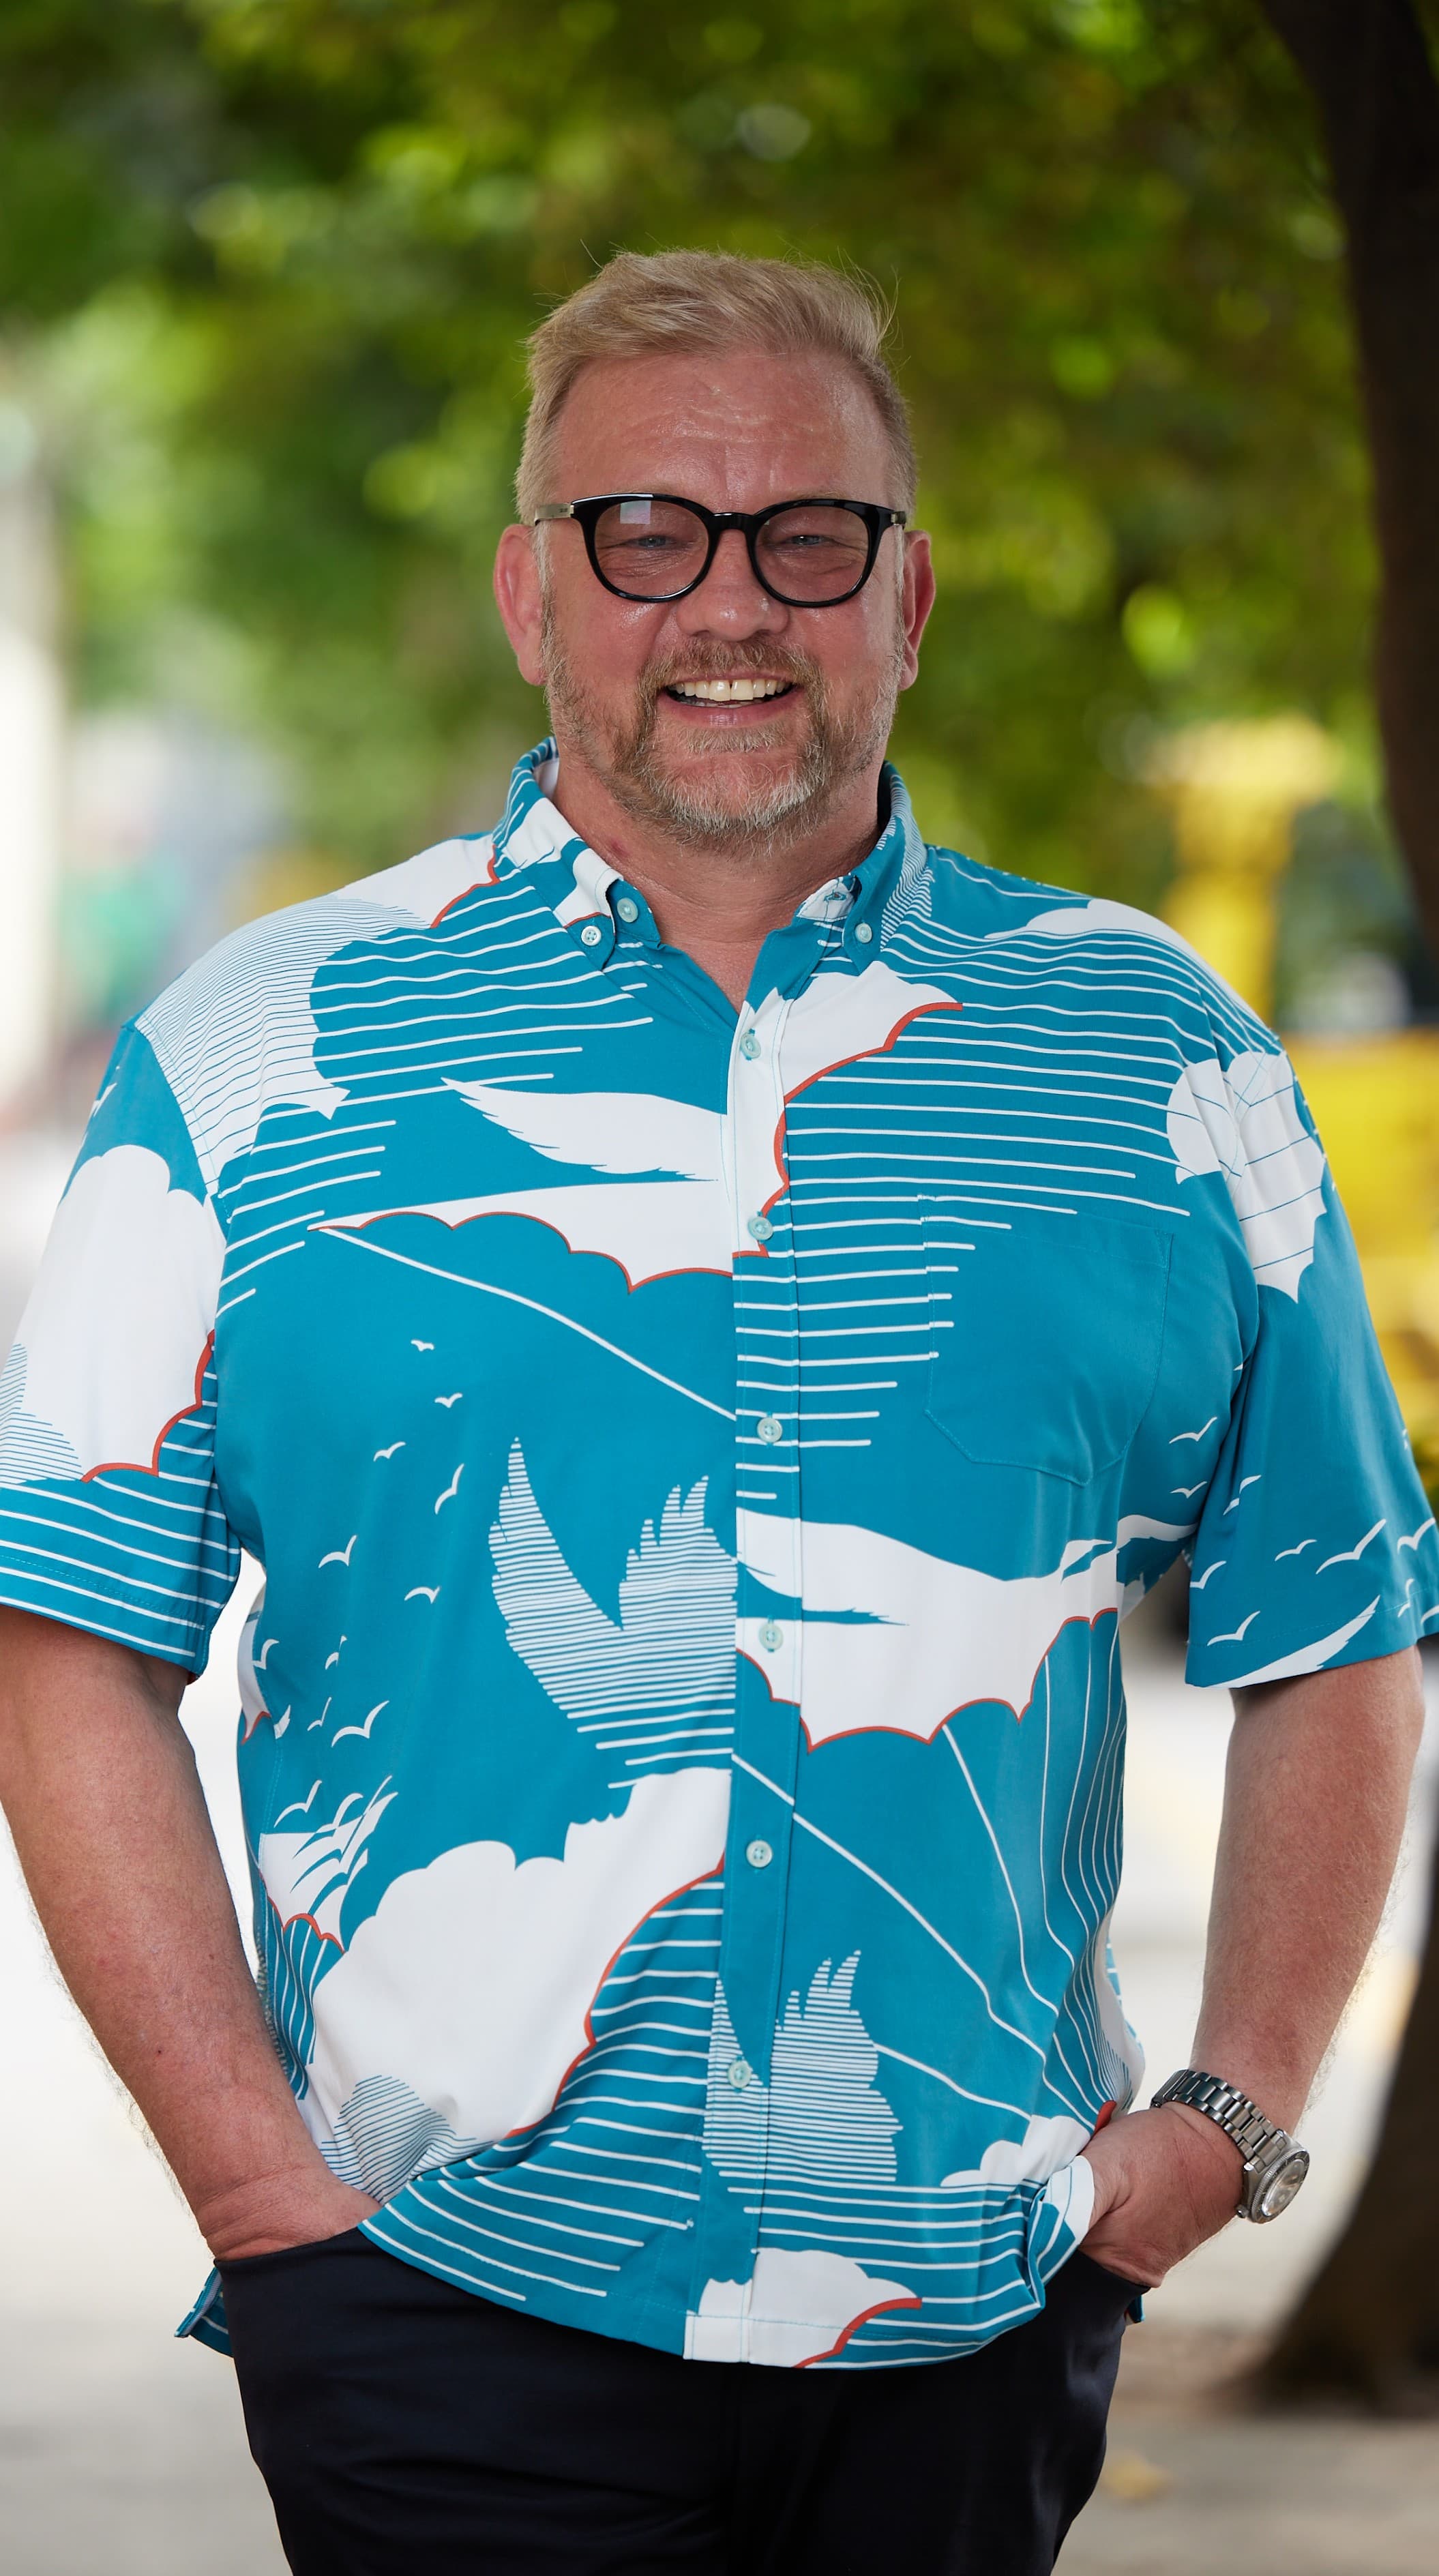
Your loan officer
Georg Thoma
Senior Loan Officer · NMLS 312260 · Licensed in Hawaiʻi, Nevada & California · English & Deutsch
This material is not from HUD or FHA and was not approved by HUD or a government agency.
Kamaʻaina Mortgage Group is not affiliated with or endorsed by HUD, FHA, or any government agency.