Business & investment-property loans
For the property that pays its own way. Qualified on the numbers that matter.
For business or investment purposes — not owner-occupied consumer mortgages. If you invest in property, a DSCR loan lets the property's own cash flow do most of the qualifying, subject to underwriting.
A DSCR loan is measured on the rent an investment property earns compared with its monthly payment, its debt-service coverage ratio, rather than on your tax returns. It suits investors buying or refinancing rentals, one property or a whole portfolio. Credit and reserves still count, and approval is subject to underwriting.
By Georg F. Thoma, Senior Loan Officer · NMLS 312260 · Updated
What I finance
DSCR investment loans
For rental and investment property, qualification is based primarily on the property's cash flow (its debt-service coverage ratio) rather than your personal income — subject to underwriting.
Business-purpose purchases
Financing to acquire or refinance investment property held for business or investment purposes. Structured around the asset and your plan for it.
Portfolio & multi-property
If you hold or are building a portfolio, we look at each property on its own merits and how the whole picture fits together.
Common questions
Still stuck? Call Georg at (808) 357-9791
What does DSCR mean?
Debt-service coverage ratio: the property's rental income divided by its monthly payment, including principal, interest, taxes, insurance and any association dues. A ratio above 1 means the rent covers the payment.
Do I need to show personal income for a DSCR loan?
The property's cash flow does most of the qualifying, so personal income documents are often limited. Your credit, reserves and the property itself are still reviewed, and everything is subject to underwriting.
Can I use a DSCR loan for a home I'll live in?
No. DSCR and other business-purpose loans are for investment property only. If you're buying a home to live in, a standard purchase or self-employed loan is the right path.
Can I finance a short-term rental with a DSCR loan?
Some programmes accept short-term rental income, subject to local rules and the programme's guidelines. In Hawaiʻi, zoning for short-term rentals matters a great deal, so check it before you buy.
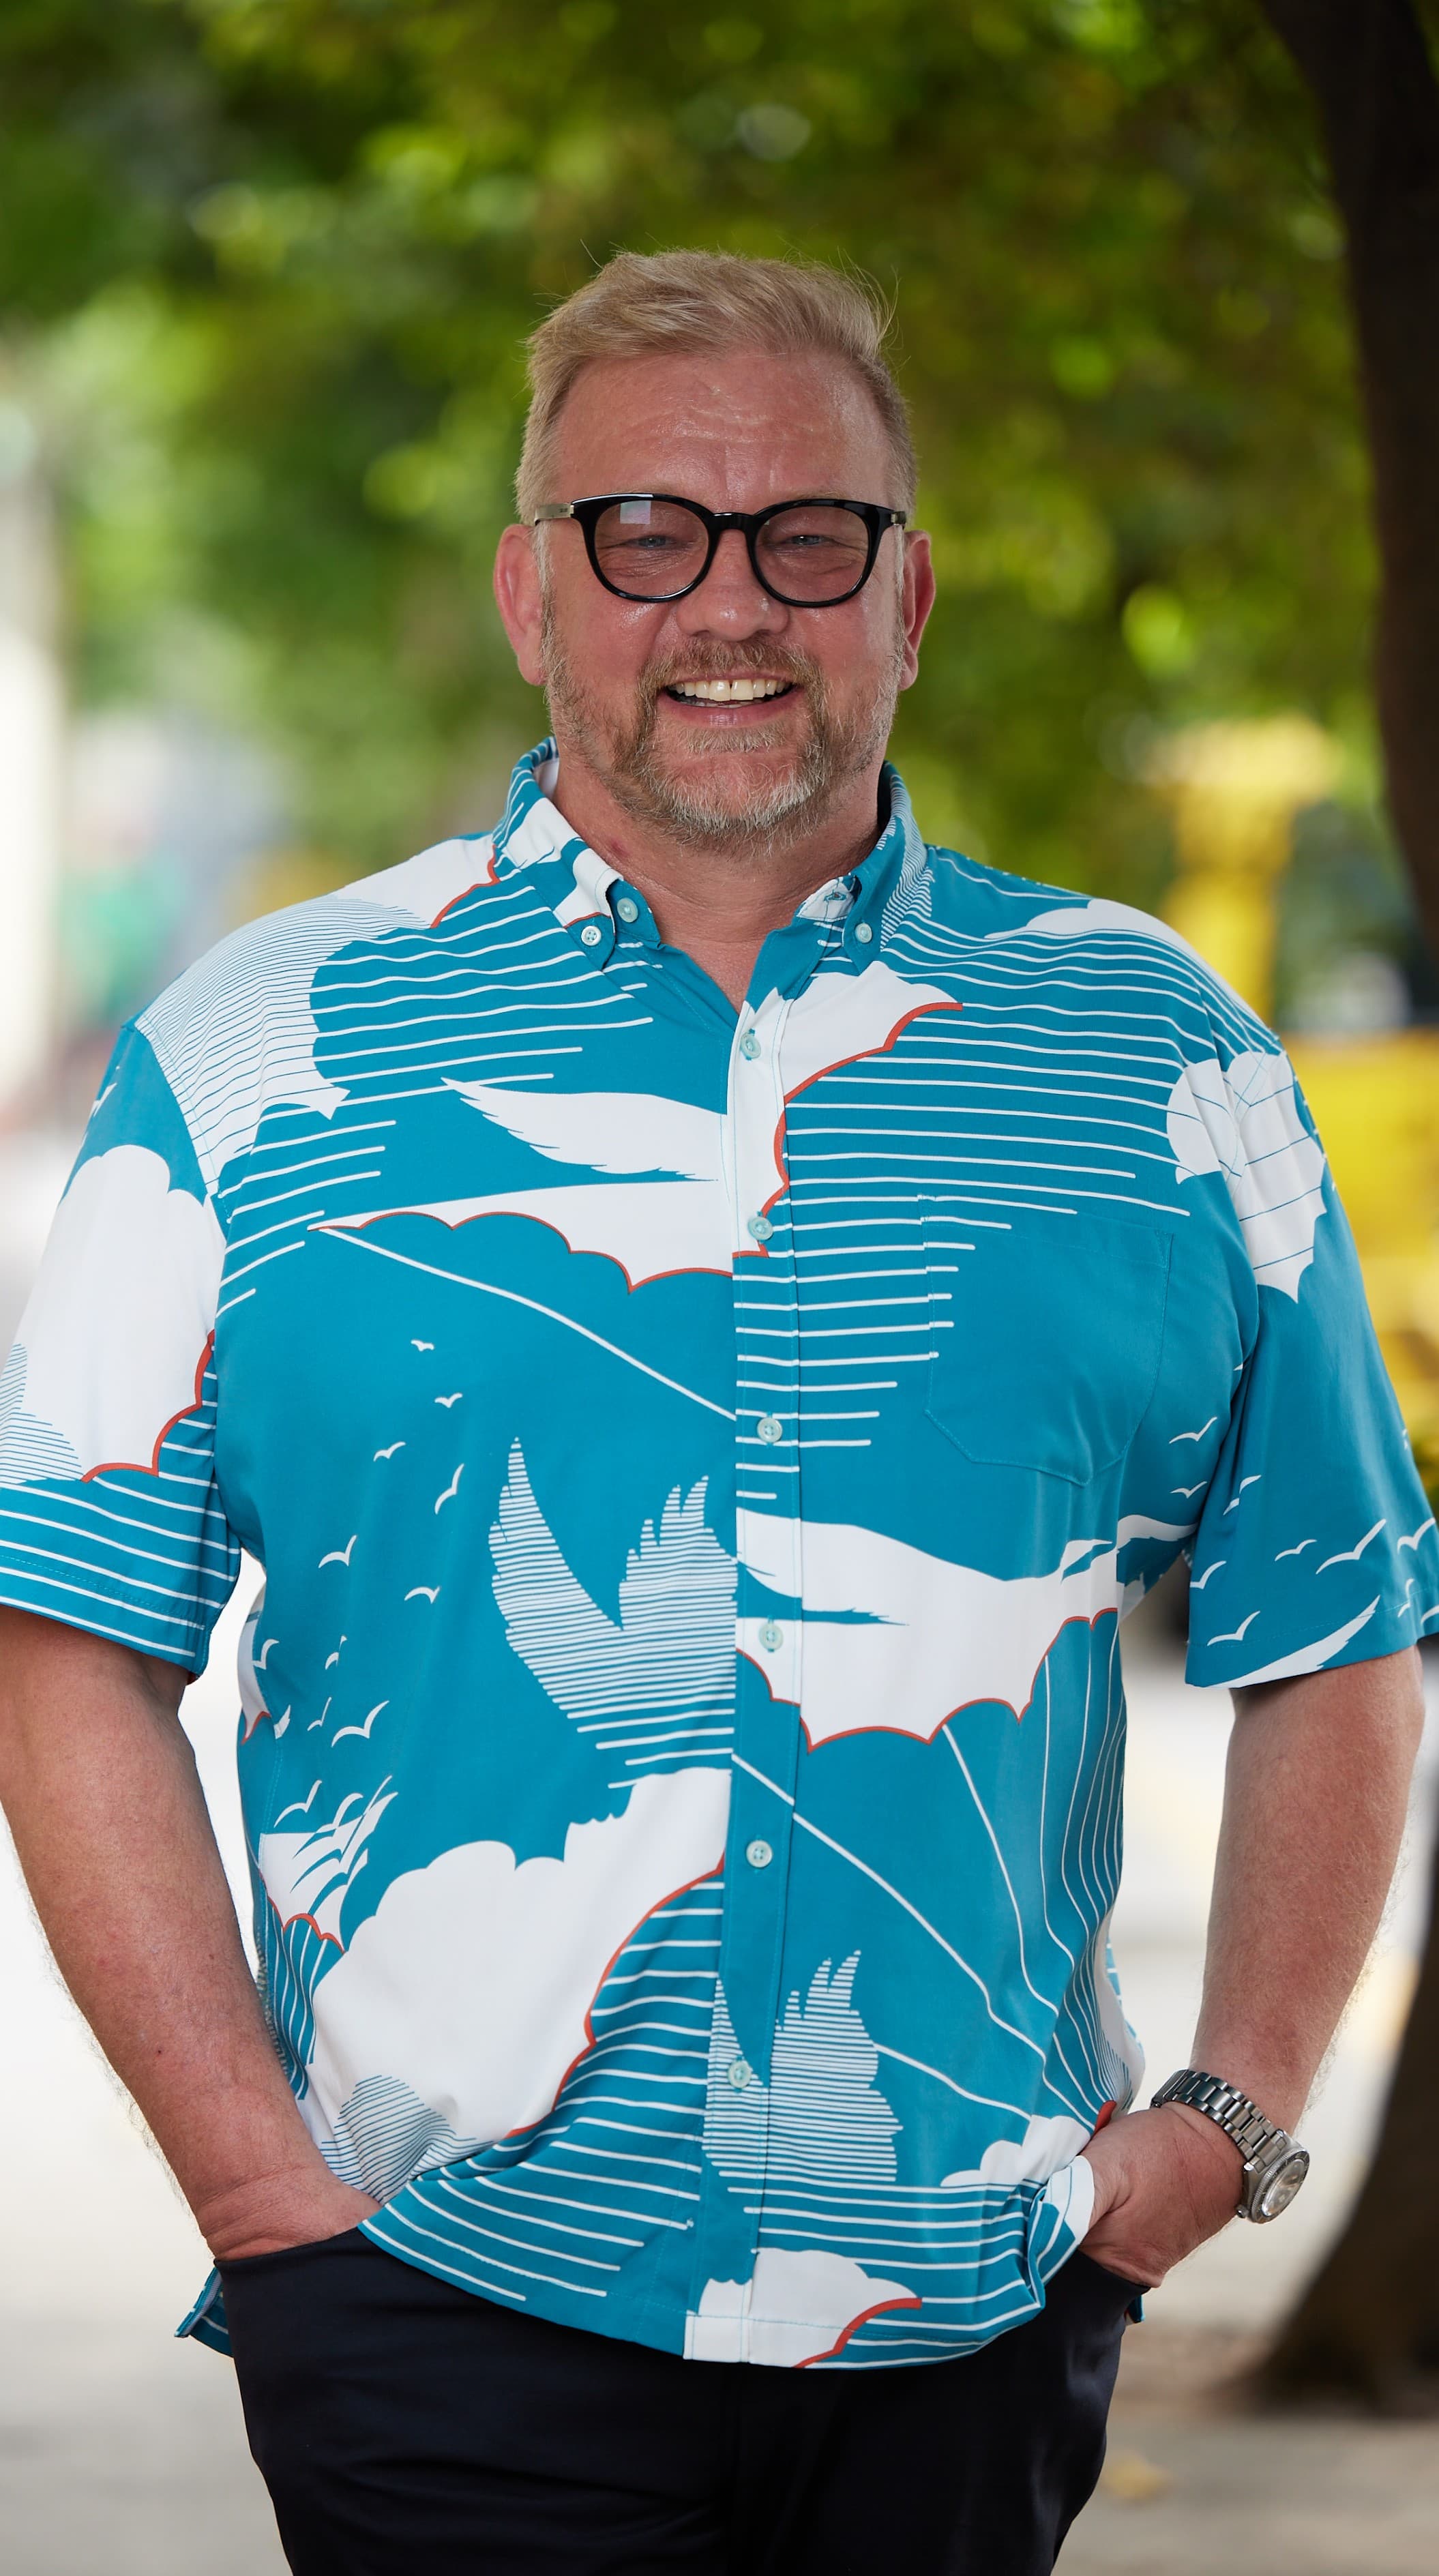
Your loan officer
Georg Thoma
Senior Loan Officer · NMLS 312260 · Licensed in Hawaiʻi, Nevada & California · English & Deutsch
Self-employed and buying a home to live in? That's a different path — see self-employed & non-traditional income.
These are business-purpose / investment-property loans, not owner-occupied consumer mortgages. Qualification is based primarily on the property's cash flow and is subject to underwriting; approval is not guaranteed. Loan programs and availability vary by state.